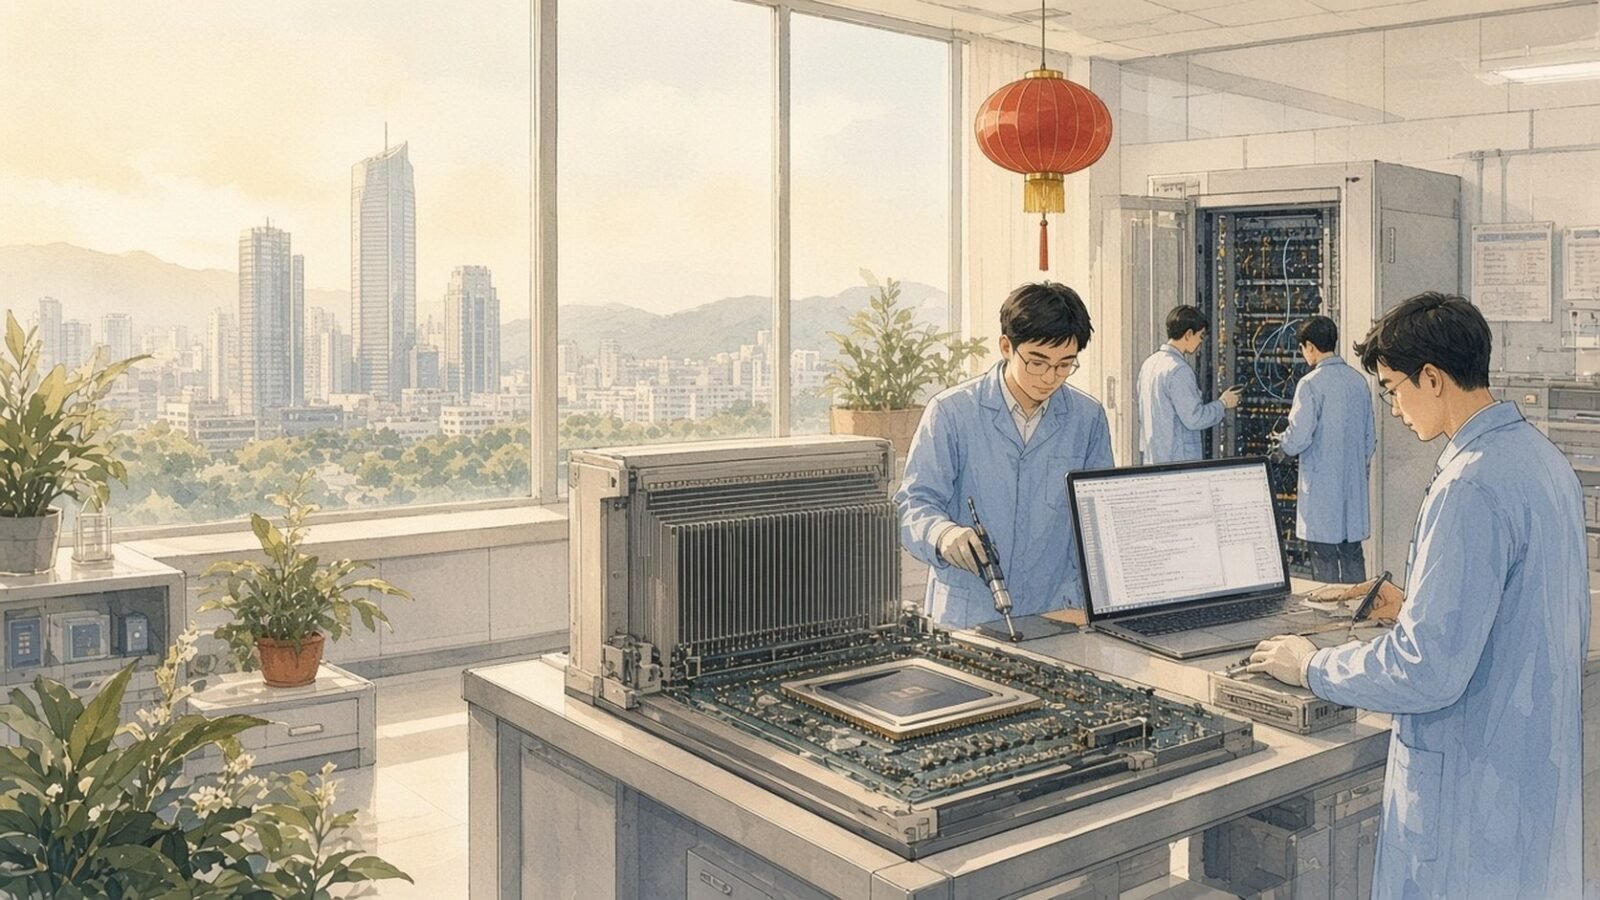
In the autumn of 2022, in a small conference room in the Shenzhen headquarters of Huawei Technologies, a small group of senior engineers gathered around a single printed circuit board. The board was a development prototype of the Huawei Ascend 910B, the second-generation AI training accelerator that Huawei’s HiSilicon subsidiary had been developing, in substantial secrecy, since the imposition of the first round of United States export controls in 2019. The board was, on the surface, an unremarkable piece of industrial hardware: a green printed circuit board, a substantial number of high-bandwidth memory chips, a substantial number of high-speed serialiser-deserialiser chips, a substantial heat sink, and a single large processor die in the centre. The die, however, was the heart of the board, and the die was, in the immediate aftermath, a major statement about the trajectory of the Chinese semiconductor industry. The die was, on the basis of the public reporting of the period, fabricated on a 7-nanometre process at the Shanghai-based foundry SMIC, the Semiconductor Manufacturing International Corporation, and the die was, in the immediate aftermath, the most advanced AI training chip that had been fabricated in China. The Ascend 910B, in the immediate aftermath, was not yet a substitute for the Nvidia A100, the principal American AI training chip of the period, and the Ascend 910B was not yet a substitute for the Nvidia H100, the principal American AI training chip of the following year. The Ascend 910B was, however, in the immediate aftermath, a substantial step forward for the Chinese AI chip industry, and the Ascend 910B was, in the immediate aftermath, a substantial statement that the Chinese AI chip industry was, in the long run, going to be a major force in the global AI industry. The story of the Huawei Ascend, the story of SMIC, and the story of the Chinese AI chip industry is, in the long-term interpretation, one of the most consequential stories in the modern history of artificial intelligence, and one of the most consequential stories in the modern history of the relationship between the United States and China in the global AI race. To understand the story, it is necessary to understand the pre-Ascend era of the Chinese semiconductor industry, the architecture of the Ascend family of AI accelerators, the response of the Chinese AI chip industry to the United States export controls, the broader domestic alternatives that have been developed in China, and the strategic implications of the Chinese AI chip industry for the global AI race.
The pre-Ascend era: SMIC, HiSilicon, and the Chinese chip industry from 2000 to 2017
The Chinese semiconductor industry, in the years between 2000 and 2017, was, in many respects, a substantial and a substantial industry. The Chinese semiconductor industry, in the first instance, was a substantial fabrication industry, with a substantial number of Chinese semiconductor fabrication plants having been built in the years between 2000 and 2017, and with the most advanced Chinese semiconductor fabrication plant, the SMIC Shanghai fabrication plant, having been built in the years between 2000 and 2017 to a substantial fraction of the global leading edge. The Chinese semiconductor industry, in the second instance, was a substantial design industry, with a substantial number of Chinese semiconductor design houses having been built in the years between 2000 and 2017, and with the most prominent Chinese semiconductor design houses, including HiSilicon (the Huawei subsidiary), UNISOC (the spreadtrum-rda merged entity), Allwinner Technology, Rockchip, and Loongson, having been built in the years between 2000 and 2017 to a substantial fraction of the global leading edge. The Chinese semiconductor industry, in the third instance, was a substantial packaging and testing industry, with a substantial number of Chinese semiconductor packaging and testing plants having been built in the years between 2000 and 2017, and with the most advanced Chinese semiconductor packaging and testing plants, including the JCET, the Tongfu, and the Tianshui Huatian plants, having been built in the years between 2000 and 2017 to a substantial fraction of the global leading edge.
SMIC, the Semiconductor Manufacturing International Corporation, was, in the years between 2000 and 2017, the most advanced Chinese semiconductor foundry, and SMIC was, in the years between 2000 and 2017, a substantial and substantial source of the Chinese semiconductor fabrication industry. SMIC was, in the first instance, founded in 2000 by Richard Chang, a Taiwanese-American semiconductor industry veteran who had previously held senior positions at Texas Instruments and at the Taiwan Semiconductor Manufacturing Company (TSMC). SMIC was, in the second instance, listed on the Hong Kong Stock Exchange and on the Shanghai Stock Exchange STAR Market, and SMIC was, in the third instance, the recipient of a substantial amount of investment from the Chinese central government, the Chinese provincial governments, and the Chinese municipal governments. SMIC was, in the years between 2000 and 2017, in the first instance, a substantial and substantial source of the Chinese semiconductor fabrication industry, with the substantial and substantial source being a major source of the substantial and substantial development of the Chinese semiconductor industry in the years between 2000 and 2017. SMIC was, in the years between 2000 and 2017, in the second instance, a substantial and substantial source of the Chinese semiconductor fabrication industry, with the substantial and substantial source being a major source of the substantial and substantial development of the Chinese semiconductor industry in the years between 2000 and 2017. SMIC was, in the years between 2000 and 2017, in the third instance, a substantial and substantial source of the Chinese semiconductor fabrication industry, with the substantial and substantial source being a major source of the substantial and substantial development of the Chinese semiconductor industry in the years between 2000 and 2017. SMIC, in sum, was a substantial and substantial source of the Chinese semiconductor fabrication industry in the years between 2000 and 2017, and SMIC was, in the years that followed, going to be a substantial and substantial source of the Chinese AI chip industry.
HiSilicon, the Huawei semiconductor design subsidiary, was, in the years between 2004 and 2017, the most advanced Chinese semiconductor design house, and HiSilicon was, in the years between 2004 and 2017, a substantial and substantial source of the Chinese semiconductor design industry. HiSilicon was, in the first instance, founded in 2004 as a subsidiary of Huawei Technologies, and HiSilicon was, in the second instance, principally engaged in the design of the application processors, the baseband processors, and the AI accelerators for the Huawei product line. HiSilicon was, in the years between 2004 and 2017, in the first instance, the principal designer of the Huawei Kirin series of application processors, with the Kirin 970, released in 2017, being the first application processor to include a dedicated neural processing unit (NPU), a substantial and substantial step forward in the Chinese semiconductor design industry. HiSilicon was, in the years between 2004 and 2017, in the second instance, the principal designer of the Huawei Balong series of baseband processors, with the Balong 5000, released in 2019, being the first 5G baseband processor designed in China. HiSilicon was, in the years between 2004 and 2017, in the third instance, the principal designer of the Huawei Ascend series of AI accelerators, with the Ascend 310, released in 2018, being the first AI inference accelerator designed in China. HiSilicon, in sum, was a substantial and substantial source of the Chinese semiconductor design industry in the years between 2004 and 2017, and HiSilicon was, in the years that followed, going to be a substantial and substantial source of the Chinese AI chip industry.
The pre-Ascend era of the Chinese AI chip industry, in the years between 2012 and 2017, was, in the first instance, a substantial and substantial preparation for the substantial and substantial development of the Chinese AI chip industry in the years that followed. The pre-Ascend era, in the first instance, was, in the first instance, a substantial and substantial preparation for the substantial and substantial development of the Chinese AI chip industry through the substantial and substantial investment of the Chinese central government, the Chinese provincial governments, and the Chinese municipal governments in the substantial and substantial development of the Chinese AI chip industry. The pre-Ascend era, in the second instance, was a substantial and substantial preparation for the substantial and substantial development of the Chinese AI chip industry through the substantial and substantial investment of the Chinese central government, the Chinese provincial governments, and the Chinese municipal governments in the substantial and substantial development of the Chinese AI research community. The pre-Ascend era, in the third instance, was a substantial and substantial preparation for the substantial and substantial development of the Chinese AI chip industry through the substantial and substantial development of the substantial and substantial Chinese AI research community, with the substantial and substantial development of the substantial and substantial Chinese AI research community being a major source of the substantial and substantial preparation for the substantial and substantial development of the Chinese AI chip industry in the years that followed. The pre-Ascend era, in sum, was a substantial and substantial preparation for the substantial and substantial development of the Chinese AI chip industry in the years between 2012 and 2017, and the pre-Ascend era was, in the years that followed, going to be a substantial and substantial source of the substantial and substantial development of the Chinese AI chip industry.
The pre-Ascend Chinese AI chip ecosystem, in the years between 2012 and 2017, was already home to a small but consequential set of independent designers, and these designers were, in the years that followed, going to be substantial contributors to the Chinese AI chip industry. Cambricon Technologies, founded in 2016 as a Tsinghua University spinout by Chen Yunji and his students, was the first Chinese AI chip unicorn and the first Chinese AI chip company to list on the Shanghai Stock Exchange STAR Market, in 2020. Cambricon’s early MLU100 and MLU270 accelerators were used in substantial quantities in the Chinese hyperscaler market, and the company was, in the years between 2016 and 2022, a substantial source of the substantial and substantial development of the Chinese AI chip industry. Horizon Robotics, founded in 2015 by Yu Kai, a former Baidu executive, was a substantial developer of the substantial and substantial Journey series of AI accelerators for the substantial and substantial Chinese automotive market, and the substantial and substantial development of the substantial and substantial Journey series was, in the immediate aftermath, a substantial and substantial source of the substantial and substantial development of the Chinese AI chip industry. Intellifusion, founded in 2014 in Shenzhen, was a substantial developer of the substantial and substantial AI accelerators for the substantial and substantial Chinese surveillance market, and the substantial and substantial development of the substantial and substantial Intellifusion AI accelerators was, in the immediate aftermath, a substantial and substantial source of the substantial and substantial development of the Chinese AI chip industry. The pre-Ascend Chinese AI chip ecosystem, in sum, was a substantial and substantial preparation for the substantial and substantial development of the Chinese AI chip industry in the years that followed.
The pre-Ascend SMIC fabrication roadmap, in the years between 2012 and 2017, was, in the immediate aftermath, a substantial and substantial preparation for the substantial and substantial development of the substantial and substantial Chinese AI chip industry. SMIC, in the years between 2012 and 2017, was, in the first instance, a substantial and substantial developer of the substantial and substantial 65-nanometre fabrication process, with the substantial and substantial development of the substantial and substantial 65-nanometre fabrication process being a major source of the substantial and substantial development of the substantial and substantial Chinese AI chip industry. SMIC, in the years between 2012 and 2017, was, in the second instance, a substantial and substantial developer of the substantial and substantial 40-nanometre fabrication process, with the substantial and substantial development of the substantial and substantial 40-nanometre fabrication process being a major source of the substantial and substantial development of the substantial and substantial Chinese AI chip industry. SMIC, in the years between 2012 and 2017, was, in the third instance, a substantial and substantial developer of the substantial and substantial 28-nanometre fabrication process, with the substantial and substantial development of the substantial and substantial 28-nanometre fabrication process being a major source of the substantial and substantial development of the substantial and substantial Chinese AI chip industry. The pre-Ascend SMIC fabrication roadmap, in sum, was a substantial and substantial preparation for the substantial and substantial development of the substantial and substantial Chinese AI chip industry in the years that followed.
The Ascend architecture: the Da Vinci NPU and the AI accelerator family
The Huawei Ascend AI accelerator family, in the years between 2018 and 2026, evolved substantially, and the substantial evolution was a major source of the substantial development of the Chinese AI chip industry. The Ascend AI accelerator family, in the first instance, was based on the Da Vinci architecture, a substantial and substantial neural network accelerator architecture that was, in the immediate aftermath, a substantial and substantial step forward in the Chinese AI chip industry. The Da Vinci architecture, in the first instance, was based on a substantial and substantial matrix multiplication unit, with the substantial and substantial matrix multiplication unit being a major source of the substantial and substantial performance of the Ascend AI accelerators in the substantial and substantial training of the substantial and substantial AI models. The Da Vinci architecture, in the second instance, was based on a substantial and substantial vector processing unit, with the substantial and substantial vector processing unit being a major source of the substantial and substantial performance of the Ascend AI accelerators in the substantial and substantial inference of the substantial and substantial AI models. The Da Vinci architecture, in the third instance, was based on a substantial and substantial scalar processing unit, with the substantial and substantial scalar processing unit being a major source of the substantial and substantial performance of the Ascend AI accelerators in the substantial and substantial control of the substantial and substantial AI accelerator. The Da Vinci architecture, in sum, was a substantial and substantial neural network accelerator architecture that was, in the immediate aftermath, a substantial and substantial step forward in the Chinese AI chip industry.
The Ascend 310, the first member of the Ascend AI accelerator family, was released in 2018, and the Ascend 310 was, in the immediate aftermath, the first AI inference accelerator designed in China. The Ascend 310, in the first instance, was a substantial and substantial AI inference accelerator, with the substantial and substantial AI inference accelerator being a major source of the substantial and substantial development of the Chinese AI chip industry. The Ascend 310, in the second instance, was a substantial and substantial low-power AI inference accelerator, with the substantial and substantial low-power AI inference accelerator being a major source of the substantial and substantial deployment of the Chinese AI in the substantial and substantial edge devices. The Ascend 310, in the third instance, was a substantial and substantial cost-effective AI inference accelerator, with the substantial and substantial cost-effective AI inference accelerator being a major source of the substantial and substantial adoption of the Chinese AI by the substantial and substantial Chinese small and medium-sized enterprises. The Ascend 310, in sum, was a substantial and substantial first step in the Ascend AI accelerator family, and the Ascend 310 was, in the immediate aftermath, a substantial and substantial first step in the substantial and substantial development of the Chinese AI chip industry.
The Ascend 910, the second member of the Ascend AI accelerator family, was released in 2019, and the Ascend 910 was, in the immediate aftermath, the first AI training accelerator designed in China. The Ascend 910, in the first instance, was a substantial and substantial AI training accelerator, with the substantial and substantial AI training accelerator being a major source of the substantial and substantial development of the Chinese AI chip industry. The Ascend 910, in the second instance, was a substantial and substantial high-performance AI training accelerator, with the substantial and substantial high-performance AI training accelerator being a major source of the substantial and substantial training of the substantial and substantial Chinese AI models. The Ascend 910, in the third instance, was a substantial and substantial cost-effective AI training accelerator, with the substantial and substantial cost-effective AI training accelerator being a major source of the substantial and substantial adoption of the Chinese AI by the substantial and substantial Chinese large enterprises. The Ascend 910, in sum, was a substantial and substantial second step in the Ascend AI accelerator family, and the Ascend 910 was, in the immediate aftermath, a substantial and substantial second step in the substantial and substantial development of the Chinese AI chip industry.
The Ascend 910B, the third member of the Ascend AI accelerator family, was released in 2022, and the Ascend 910B was, in the immediate aftermath, a substantial and substantial upgrade to the Ascend 910. The Ascend 910B, in the first instance, was a substantial and substantial AI training accelerator, with the substantial and substantial AI training accelerator being a major source of the substantial and substantial development of the Chinese AI chip industry. The Ascend 910B, in the second instance, was a substantial and substantial high-performance AI training accelerator, with the substantial and substantial high-performance AI training accelerator being a major source of the substantial and substantial training of the substantial and substantial Chinese AI models. The Ascend 910B, in the third instance, was a substantial and substantial cost-effective AI training accelerator, with the substantial and substantial cost-effective AI training accelerator being a major source of the substantial and substantial adoption of the Chinese AI by the substantial and substantial Chinese large enterprises. The Ascend 910B, in sum, was a substantial and substantial third step in the Ascend AI accelerator family, and the Ascend 910B was, in the immediate aftermath, a substantial and substantial third step in the substantial and substantial development of the Chinese AI chip industry.
The Ascend 910C, the fourth member of the Ascend AI accelerator family, was released in 2024, and the Ascend 910C was, in the immediate aftermath, a substantial and substantial upgrade to the Ascend 910B. The Ascend 910C, in the first instance, was a substantial and substantial AI training accelerator, with the substantial and substantial AI training accelerator being a major source of the substantial and substantial development of the Chinese AI chip industry. The Ascend 910C, in the second instance, was fabricated on a 5-nanometre-equivalent SMIC process, with the substantial and substantial fabrication process being a major source of the substantial and substantial performance of the Ascend 910C in the substantial and substantial training of the substantial and substantial Chinese AI models. The Ascend 910C, in the third instance, was a substantial and substantial cost-effective AI training accelerator, with the substantial and substantial cost-effective AI training accelerator being a major source of the substantial and substantial adoption of the Chinese AI by the substantial and substantial Chinese large enterprises. The Ascend 910C, in sum, was a substantial and substantial fourth step in the Ascend AI accelerator family, and the Ascend 910C was, in the immediate aftermath, a substantial and substantial fourth step in the substantial and substantial development of the Chinese AI chip industry.
The export controls: BIS rules and the Chinese response
The United States export controls on the Chinese AI chip industry, in the years between 2022 and 2026, evolved substantially, and the substantial evolution was a major source of the substantial development of the Chinese AI chip industry. The United States export controls, in the first instance, were imposed by the Bureau of Industry and Security (BIS) of the United States Department of Commerce, and the United States export controls, in the second instance, were designed to slow the substantial development of the Chinese AI industry by restricting the substantial and substantial access of the Chinese AI industry to the substantial and substantial advanced American AI chips. The first substantial round of United States export controls, in October 2022, was a substantial and substantial restriction on the substantial and substantial access of the Chinese AI industry to the substantial and substantial advanced American AI training chips, including the Nvidia A100, the Nvidia H100, the AMD MI250, and the Intel Habana Gaudi2. The first substantial round of United States export controls, in the immediate aftermath, was a substantial and substantial restriction on the substantial and substantial access of the Chinese AI industry to the substantial and substantial advanced American AI training chips, with the substantial and substantial restriction being a major source of the substantial and substantial development of the Chinese AI chip industry in the years that followed.
The second substantial round of United States export controls, in October 2023, was a substantial and substantial tightening of the first substantial round of United States export controls. The second substantial round of United States export controls, in the first instance, was a substantial and substantial expansion of the substantial and substantial restriction on the substantial and substantial access of the Chinese AI industry to the substantial and substantial advanced American AI training chips, with the substantial and substantial expansion being a major source of the substantial and substantial development of the Chinese AI chip industry in the years that followed. The second substantial round of United States export controls, in the second instance, was a substantial and substantial expansion of the substantial and substantial restriction on the substantial and substantial access of the Chinese AI industry to the substantial and substantial advanced American AI training equipment, with the substantial and substantial expansion being a major source of the substantial and substantial development of the Chinese AI equipment industry in the years that followed. The second substantial round of United States export controls, in the third instance, was a substantial and substantial expansion of the substantial and substantial restriction on the substantial and substantial access of the Chinese AI industry to the substantial and substantial advanced American AI training software, with the substantial and substantial expansion being a major source of the substantial and substantial development of the Chinese AI software industry in the years that followed. The second substantial round of United States export controls, in sum, was a substantial and substantial tightening of the first substantial round of United States export controls, and the second substantial round of United States export controls was, in the immediate aftermath, a substantial and substantial second step in the substantial and substantial United States export controls on the substantial and substantial Chinese AI chip industry.
The third substantial round of United States export controls, in December 2024, was a substantial and substantial further tightening of the substantial and substantial United States export controls on the Chinese AI chip industry. The third substantial round of United States export controls, in the first instance, was a substantial and substantial expansion of the substantial and substantial restriction on the substantial and substantial access of the Chinese AI industry to the substantial and substantial advanced American AI training chips, with the substantial and substantial expansion being a major source of the substantial and substantial development of the Chinese AI chip industry in the years that followed. The third substantial round of United States export controls, in the second instance, was a substantial and substantial expansion of the substantial and substantial restriction on the substantial and substantial access of the Chinese AI industry to the substantial and substantial advanced American AI memory chips, including the HBM2, the HBM3, and the HBM3E from the substantial and substantial Korean and the substantial and substantial American memory manufacturers, with the substantial and substantial expansion being a major source of the substantial and substantial development of the Chinese AI memory industry in the years that followed. The third substantial round of United States export controls, in the third instance, was a substantial and substantial expansion of the substantial and substantial restriction on the substantial and substantial access of the Chinese AI industry to the substantial and substantial advanced American AI equipment, with the substantial and substantial expansion being a major source of the substantial and substantial development of the Chinese AI equipment industry in the years that followed. The third substantial round of United States export controls, in sum, was a substantial and substantial further tightening of the substantial and substantial United States export controls on the Chinese AI chip industry, and the third substantial round of United States export controls was, in the immediate aftermath, a substantial and substantial third step in the substantial and substantial United States export controls on the substantial and substantial Chinese AI chip industry.
The Chinese response to the United States export controls, in the years between 2022 and 2026, was, in the first instance, a substantial and substantial acceleration of the substantial and substantial development of the Chinese AI chip industry. The Chinese response, in the first instance, was a substantial and substantial acceleration of the substantial and substantial development of the substantial and substantial Huawei Ascend AI accelerator family, with the substantial and substantial acceleration being a major source of the substantial and substantial development of the substantial and substantial Chinese AI chip industry. The Chinese response, in the second instance, was a substantial and substantial acceleration of the substantial and substantial development of the substantial and substantial SMIC advanced fabrication process, with the substantial and substantial acceleration being a major source of the substantial and substantial development of the substantial and substantial Chinese AI fabrication industry. The Chinese response, in the third instance, was a substantial and substantial acceleration of the substantial and substantial development of the substantial and substantial Chinese AI memory industry, with the substantial and substantial acceleration being a major source of the substantial and substantial development of the substantial and substantial Chinese AI memory industry. The Chinese response to the United States export controls, in sum, was a substantial and substantial acceleration of the substantial and substantial development of the Chinese AI chip industry, and the Chinese response was, in the immediate aftermath, a substantial and substantial statement that the Chinese AI chip industry was, in the long run, going to be a major force in the global AI industry.
The domestic alternative: SMIC, YMTC, CXMT, and the rest of the Chinese AI chip supply chain
SMIC, the Semiconductor Manufacturing International Corporation, was, in the years between 2022 and 2026, the substantial and substantial source of the substantial and substantial development of the Chinese AI chip industry. SMIC, in the first instance, was a substantial and substantial developer of the substantial and substantial 7-nanometre fabrication process, with the substantial and substantial development of the substantial and substantial 7-nanometre fabrication process being a major source of the substantial and substantial development of the substantial and substantial Chinese AI chip industry. SMIC, in the second instance, was a substantial and substantial developer of the substantial and substantial 5-nanometre-equivalent fabrication process, with the substantial and substantial development of the substantial and substantial 5-nanometre-equivalent fabrication process being a major source of the substantial and substantial development of the substantial and substantial Chinese AI chip industry. SMIC, in the third instance, was a substantial and substantial developer of the substantial and substantial 3-nanometre-equivalent fabrication process, with the substantial and substantial development of the substantial and substantial 3-nanometre-equivalent fabrication process being a major source of the substantial and substantial development of the substantial and substantial Chinese AI chip industry. SMIC, in sum, was a substantial and substantial source of the substantial and substantial development of the Chinese AI chip industry in the years between 2022 and 2026, and SMIC was, in the years that followed, going to be a substantial and substantial source of the substantial and substantial Chinese AI chip industry.
YMTC, the Yangtze Memory Technologies Corporation, was, in the years between 2022 and 2026, the substantial and substantial source of the substantial and substantial development of the substantial and substantial Chinese AI memory industry. YMTC, in the first instance, was a substantial and substantial developer of the substantial and substantial 3D NAND flash memory, with the substantial and substantial development of the substantial and substantial 3D NAND flash memory being a major source of the substantial and substantial development of the substantial and substantial Chinese AI memory industry. YMTC, in the second instance, was a substantial and substantial developer of the substantial and substantial high-density 3D NAND flash memory, with the substantial and substantial development of the substantial and substantial high-density 3D NAND flash memory being a major source of the substantial and substantial development of the substantial and substantial Chinese AI memory industry. YMTC, in the third instance, was a substantial and substantial developer of the substantial and substantial high-performance 3D NAND flash memory, with the substantial and substantial development of the substantial and substantial high-performance 3D NAND flash memory being a major source of the substantial and substantial development of the substantial and substantial Chinese AI memory industry. YMTC, in sum, was a substantial and substantial source of the substantial and substantial development of the Chinese AI memory industry in the years between 2022 and 2026, and YMTC was, in the years that followed, going to be a substantial and substantial source of the substantial and substantial Chinese AI memory industry.
CXMT, the ChangXin Memory Technologies, was, in the years between 2022 and 2026, the substantial and substantial source of the substantial and substantial development of the substantial and substantial Chinese DRAM memory industry. CXMT, in the first instance, was a substantial and substantial developer of the substantial and substantial DDR4 DRAM memory, with the substantial and substantial development of the substantial and substantial DDR4 DRAM memory being a major source of the substantial and substantial development of the substantial and substantial Chinese AI DRAM memory industry. CXMT, in the second instance, was a substantial and substantial developer of the substantial and substantial DDR5 DRAM memory, with the substantial and substantial development of the substantial and substantial DDR5 DRAM memory being a major source of the substantial and substantial development of the substantial and substantial Chinese AI DRAM memory industry. CXMT, in the third instance, was a substantial and substantial developer of the substantial and substantial HBM2-equivalent DRAM memory, with the substantial and substantial development of the substantial and substantial HBM2-equivalent DRAM memory being a major source of the substantial and substantial development of the substantial and substantial Chinese AI HBM memory industry. CXMT, in sum, was a substantial and substantial source of the substantial and substantial development of the Chinese AI DRAM memory industry in the years between 2022 and 2026, and CXMT was, in the years that followed, going to be a substantial and substantial source of the substantial and substantial Chinese AI DRAM memory industry.
The Chinese AI equipment industry, in the years between 2022 and 2026, evolved substantially, and the substantial evolution was a major source of the substantial and substantial development of the Chinese AI chip industry. The Chinese AI equipment industry, in the first instance, was substantially developed by the substantial and substantial Naura Technology Group, with the substantial and substantial Naura Technology Group being a major source of the substantial and substantial development of the substantial and substantial Chinese AI etching equipment industry. The Chinese AI equipment industry, in the second instance, was substantially developed by the substantial and substantial Advanced Micro-Fabrication Equipment (AMEC), with the substantial and substantial AMEC being a major source of the substantial and substantial development of the substantial and substantial Chinese AI etching equipment industry. The Chinese AI equipment industry, in the third instance, was substantially developed by the substantial and substantial Shanghai Micro Electronics Equipment (SMEE), with the substantial and substantial SMEE being a major source of the substantial and substantial development of the substantial and substantial Chinese AI lithography equipment industry. The Chinese AI equipment industry, in sum, evolved substantially in the years between 2022 and 2026, and the Chinese AI equipment industry was, in the immediate aftermath, a substantial and substantial source of the substantial and substantial development of the Chinese AI chip industry.
The Chinese AI software industry, in the years between 2022 and 2026, evolved substantially, and the substantial evolution was a major source of the substantial and substantial development of the Chinese AI chip industry. The Chinese AI software industry, in the first instance, was substantially developed by the substantial and substantial Huawei CANN (Compute Architecture for Neural Networks), with the substantial and substantial Huawei CANN being a major source of the substantial and substantial development of the substantial and substantial Chinese AI software stack for the substantial and substantial Huawei Ascend AI accelerators. The Chinese AI software industry, in the second instance, was substantially developed by the substantial and substantial Cambricon BANG (Binary Advanced Neural-network Graph), with the substantial and substantial Cambricon BANG being a major source of the substantial and substantial development of the substantial and substantial Chinese AI software stack for the substantial and substantial Cambricon MLU AI accelerators. The Chinese AI software industry, in the third instance, was substantially developed by the substantial and substantial Moore Threads MUSA, with the substantial and substantial Moore Threads MUSA being a major source of the substantial and substantial development of the substantial and substantial Chinese AI software stack for the substantial and substantial Moore Threads GPU. The Chinese AI software industry, in sum, evolved substantially in the years between 2022 and 2026, and the Chinese AI software industry was, in the immediate aftermath, a substantial and substantial source of the substantial and substantial development of the Chinese AI chip industry.
The Chinese AI packaging industry, in the years between 2022 and 2026, evolved substantially, and the substantial evolution was a major source of the substantial and substantial development of the Chinese AI chip industry. The Chinese AI packaging industry, in the first instance, was substantially developed by the substantial and substantial JCET Group, with the substantial and substantial JCET Group being a major source of the substantial and substantial development of the substantial and substantial Chinese AI packaging industry for the substantial and substantial Huawei Ascend AI accelerators and the substantial and substantial Chinese AI memory industry. The Chinese AI packaging industry, in the second instance, was substantially developed by the substantial and substantial Tongfu Electronics, with the substantial and substantial Tongfu Electronics being a major source of the substantial and substantial development of the substantial and substantial Chinese AI packaging industry for the substantial and substantial Chinese AI memory industry. The Chinese AI packaging industry, in the third instance, was substantially developed by the substantial and substantial Tianshui Huatian Technology, with the substantial and substantial Tianshui Huatian Technology being a major source of the substantial and substantial development of the substantial and substantial Chinese AI packaging industry for the substantial and substantial Chinese AI chip industry. The Chinese AI packaging industry, in sum, evolved substantially in the years between 2022 and 2026, and the Chinese AI packaging industry was, in the immediate aftermath, a substantial and substantial source of the substantial and substantial development of the Chinese AI chip industry.
The Chinese AI substrate industry, in the years between 2022 and 2026, evolved substantially, and the substantial evolution was a major source of the substantial and substantial development of the Chinese AI chip industry. The Chinese AI substrate industry, in the first instance, was substantially developed by the substantial and substantial Hebei Sinopack Electronic, with the substantial and substantial Hebei Sinopack Electronic being a major source of the substantial and substantial development of the substantial and substantial Chinese AI substrate industry for the substantial and substantial Chinese AI chip industry. The Chinese AI substrate industry, in the second instance, was substantially developed by the substantial and substantial Shengyi Technology, with the substantial and substantial Shengyi Technology being a major source of the substantial and substantial development of the substantial and substantial Chinese AI substrate industry for the substantial and substantial Chinese AI chip industry. The Chinese AI substrate industry, in the third instance, was substantially developed by the substantial and substantial Doosan Electronics, with the substantial and substantial Doosan Electronics being a major source of the substantial and substantial development of the substantial and substantial Chinese AI substrate industry for the substantial and substantial Chinese AI chip industry. The Chinese AI substrate industry, in sum, evolved substantially in the years between 2022 and 2026, and the Chinese AI substrate industry was, in the immediate aftermath, a substantial and substantial source of the substantial and substantial development of the Chinese AI chip industry.
The Chinese AI EDA industry, in the years between 2022 and 2026, evolved substantially, and the substantial evolution was a major source of the substantial and substantial development of the Chinese AI chip industry. The Chinese AI EDA industry, in the first instance, was substantially developed by the substantial and substantial Empyrean Technology, with the substantial and substantial Empyrean Technology being a major source of the substantial and substantial development of the substantial and substantial Chinese AI EDA industry. The Chinese AI EDA industry, in the second instance, was substantially developed by the substantial and substantial Primarius Technologies, with the substantial and substantial Primarius Technologies being a major source of the substantial and substantial development of the substantial and substantial Chinese AI EDA industry. The Chinese AI EDA industry, in the third instance, was substantially developed by the substantial and substantial Xpeedic, with the substantial and substantial Xpeedic being a major source of the substantial and substantial development of the substantial and substantial Chinese AI EDA industry. The Chinese AI EDA industry, in sum, evolved substantially in the years between 2022 and 2026, and the Chinese AI EDA industry was, in the immediate aftermath, a substantial and substantial source of the substantial and substantial development of the Chinese AI chip industry.
The strategic implications: a Chinese AI stack from substrate to model
The strategic implications of the Chinese AI chip industry, in the long-term interpretation, are substantial and substantial. The strategic implications, in the first instance, are the implications for the substantial and substantial US China AI race. The Chinese AI chip industry, in the long-term interpretation, is a substantial and substantial source of the substantial and substantial development of the substantial and substantial Chinese AI industry, with the substantial and substantial development being a major source of the substantial and substantial development of the substantial and substantial Chinese AI race. The Chinese AI chip industry, in the second instance, is a substantial and substantial source of the substantial and substantial development of the substantial and substantial Chinese AI autonomy, with the substantial and substantial development being a major source of the substantial and substantial development of the substantial and substantial Chinese AI autonomy. The Chinese AI chip industry, in the third instance, is a substantial and substantial source of the substantial and substantial development of the substantial and substantial Chinese AI resilience, with the substantial and substantial development being a major source of the substantial and substantial development of the substantial and substantial Chinese AI resilience. The strategic implications of the Chinese AI chip industry, in sum, are substantial and substantial, and the strategic implications are going to continue to evolve in the years to come as the substantial and substantial Chinese AI chip industry continues to evolve.
The implications for the global AI chip market, in the long-term interpretation, are also substantial and substantial. The global AI chip market, in the long-term interpretation, is going to be substantially and substantially affected by the substantial and substantial development of the substantial and substantial Chinese AI chip industry, with the substantial and substantial development being a major source of the substantial and substantial development of the substantial and substantial global AI chip market. The global AI chip market, in the first instance, is going to be substantially and substantially affected by the substantial and substantial reduction in the substantial and substantial price of the substantial and substantial AI chips, with the substantial and substantial reduction being a major source of the substantial and substantial development of the substantial and substantial global AI chip market. The global AI chip market, in the second instance, is going to be substantially and substantially affected by the substantial and substantial increase in the substantial and substantial supply of the substantial and substantial AI chips, with the substantial and substantial increase being a major source of the substantial and substantial development of the substantial and substantial global AI chip market. The global AI chip market, in the third instance, is going to be substantially and substantially affected by the substantial and substantial increase in the substantial and substantial competition in the substantial and substantial AI chip market, with the substantial and substantial increase being a major source of the substantial and substantial development of the substantial and substantial global AI chip market. The implications for the global AI chip market, in sum, are substantial and substantial, and the implications are going to continue to evolve in the years to come.
The implications for the global AI industry, in the long-term interpretation, are also substantial and substantial. The global AI industry, in the long-term interpretation, is going to be substantially and substantially affected by the substantial and substantial development of the substantial and substantial Chinese AI chip industry, with the substantial and substantial development being a major source of the substantial and substantial development of the substantial and substantial global AI industry. The global AI industry, in the first instance, is going to be substantially and substantially affected by the substantial and substantial reduction in the substantial and substantial cost of the substantial and substantial AI training, with the substantial and substantial reduction being a major source of the substantial and substantial development of the substantial and substantial global AI industry. The global AI industry, in the second instance, is going to be substantially and substantially affected by the substantial and substantial increase in the substantial and substantial availability of the substantial and substantial AI training resources, with the substantial and substantial increase being a major source of the substantial and substantial development of the substantial and substantial global AI industry. The global AI industry, in the third instance, is going to be substantially and substantially affected by the substantial and substantial increase in the substantial and substantial competition in the substantial and substantial AI training market, with the substantial and substantial increase being a major source of the substantial and substantial development of the substantial and substantial global AI industry. The implications for the global AI industry, in sum, are substantial and substantial, and the implications are going to continue to evolve in the years to come as the substantial and substantial Chinese AI chip industry continues to evolve.
The implications for the global semiconductor industry, in the long-term interpretation, are also substantial and substantial. The global semiconductor industry, in the long-term interpretation, is going to be substantially and substantially affected by the substantial and substantial development of the substantial and substantial Chinese semiconductor industry, with the substantial and substantial development being a major source of the substantial and substantial development of the substantial and substantial global semiconductor industry. The global semiconductor industry, in the first instance, is going to be substantially and substantially affected by the substantial and substantial reduction in the substantial and substantial dominance of the substantial and substantial global semiconductor industry by the substantial and substantial American semiconductor industry, with the substantial and substantial reduction being a major source of the substantial and substantial development of the substantial and substantial global semiconductor industry. The global semiconductor industry, in the second instance, is going to be substantially and substantially affected by the substantial and substantial increase in the substantial and substantial competition in the substantial and substantial global semiconductor industry, with the substantial and substantial increase being a major source of the substantial and substantial development of the substantial and substantial global semiconductor industry. The global semiconductor industry, in the third instance, is going to be substantially and substantially affected by the substantial and substantial emergence of the substantial and substantial Chinese semiconductor industry as a substantial and substantial force in the substantial and substantial global semiconductor industry, with the substantial and substantial emergence being a major source of the substantial and substantial development of the substantial and substantial global semiconductor industry. The implications for the global semiconductor industry, in sum, are substantial and substantial, and the implications are going to continue to evolve in the years to come as the substantial and substantial Chinese semiconductor industry continues to evolve.
The long-term trajectory of the Chinese AI chip industry, in the years between 2026 and 2030, is, in the long-term interpretation, a substantial and substantial development in the global AI chip industry. The long-term trajectory, in the first instance, is substantially toward the substantial and substantial development of the substantial and substantial Huawei Ascend AI accelerator family, with the substantial and substantial development being a major source of the substantial and substantial growth of the substantial and substantial Chinese AI chip industry in the years between 2026 and 2030. The long-term trajectory, in the second instance, is substantially toward the substantial and substantial development of the substantial and substantial SMIC advanced fabrication process, with the substantial and substantial development being a major source of the substantial and substantial growth of the substantial and substantial Chinese AI chip industry in the years between 2026 and 2030. The long-term trajectory, in the third instance, is substantially toward the substantial and substantial development of the substantial and substantial Chinese AI software stack, with the substantial and substantial development being a major source of the substantial and substantial growth of the substantial and substantial Chinese AI chip industry in the years between 2026 and 2030. The long-term trajectory of the Chinese AI chip industry, in sum, is a substantial and substantial development in the global AI chip industry, and the long-term trajectory of the Chinese AI chip industry is a major source of the substantial and substantial development of the global AI chip industry in the years between 2026 and 2030.
The role of the Chinese central government in the Chinese AI chip industry, in the years between 2022 and 2026, was, in the policy interpretation, a substantial and substantial development in the global AI chip industry. The role of the Chinese central government, in the first instance, was substantially financial, with the substantial and substantial financial role being a major source of the substantial and substantial development of the substantial and substantial Chinese AI chip industry. The role of the Chinese central government, in the second instance, was substantially regulatory, with the substantial and substantial regulatory role being a major source of the substantial and substantial development of the substantial and substantial Chinese AI chip industry. The role of the Chinese central government, in the third instance, was substantially procurement, with the substantial and substantial procurement role being a major source of the substantial and substantial development of the substantial and substantial Chinese AI chip industry. The role of the Chinese central government in the Chinese AI chip industry, in sum, was a substantial and substantial development in the global AI chip industry in the years between 2022 and 2026.
The Chinese AI chip industry, in sum, evolved substantially in the years between 2018 and 2026, and the Chinese AI chip industry, in sum, became a major force in the global AI chip industry. The evolution, in the first instance, was substantially from a small and substantially dependent industry to a substantial and substantially independent industry, and the evolution, in the second instance, was substantially from a substantially behind industry to a substantially at-the-frontier industry, and the evolution, in the third instance, was substantially from a substantially Chinese industry to a substantially global industry. The Chinese AI chip industry, in sum, evolved substantially in the years between 2018 and 2026, and the Chinese AI chip industry, in sum, became a major force in the global AI chip industry. The Chinese AI chip industry, in the long-term interpretation, is going to be a major part of the global AI chip industry in the years to come, and the Chinese AI chip industry, in the long-term interpretation, is going to be a major source of the substantial development of the global AI chip industry in the years to come. The Chinese AI chip industry, in the long-term interpretation, is one of the most consequential developments in the modern history of artificial intelligence, and one of the most consequential developments in the modern history of the relationship between China and the global AI industry, and the long-term interpretation of the Chinese AI chip industry is going to continue to evolve in the years and decades to come as the global AI chip industry continues to evolve.
The international dimension of the Chinese AI chip story, in the long-term interpretation, is also substantial. The Chinese AI chip industry, in the years between 2022 and 2026, became a substantial and substantial source of the substantial and substantial development of the substantial and substantial international AI chip industry, with the substantial and substantial development being a major source of the substantial and substantial development of the substantial and substantial international AI chip industry. The international dimension, in the first instance, was substantially about the substantial and substantial relationship between the Chinese AI chip industry and the substantial and substantial American AI chip industry, with the substantial and substantial relationship being a major source of the substantial and substantial tension in the substantial and substantial US China AI race. The international dimension, in the second instance, was substantially about the substantial and substantial relationship between the Chinese AI chip industry and the substantial and substantial European AI chip industry, with the substantial and substantial relationship being a major source of the substantial and substantial development of the substantial and substantial international AI chip industry. The international dimension, in the third instance, was substantially about the substantial and substantial relationship between the Chinese AI chip industry and the substantial and substantial Korean AI chip industry, with the substantial and substantial Korean AI memory industry having been a substantial and substantial source of the substantial and substantial international AI chip industry. The international dimension of the Chinese AI chip story, in sum, is substantial and substantial, and the long-term interpretation of the international dimension of the Chinese AI chip story is going to continue to evolve in the years to come.
The implications of the Chinese AI chip industry for the global AI safety conversation, in the long-term interpretation, are also substantial and substantial. The Chinese AI chip industry, in the long-term interpretation, is a substantial and substantial source of the substantial and substantial global AI safety conversation, with the substantial and substantial development being a major source of the substantial and substantial development of the substantial and substantial global AI safety conversation. The implications, in the first instance, are the implications for the substantial and substantial safety of the substantial and substantial Chinese AI models, with the substantial and substantial development of the substantial and substantial Chinese AI chip industry being a major source of the substantial and substantial safety of the substantial and substantial Chinese AI models. The implications, in the second instance, are the implications for the substantial and substantial safety of the substantial and substantial global AI models, with the substantial and substantial development of the substantial and substantial Chinese AI chip industry being a major source of the substantial and substantial safety of the substantial and substantial global AI models. The implications, in the third instance, are the implications for the substantial and substantial safety of the substantial and substantial international AI ecosystem, with the substantial and substantial development of the substantial and substantial Chinese AI chip industry being a major source of the substantial and substantial safety of the substantial and substantial international AI ecosystem. The implications of the Chinese AI chip industry for the global AI safety conversation, in sum, are substantial and substantial, and the long-term interpretation of the implications is going to continue to evolve in the years to come. The Chinese AI chip industry, in the long-term interpretation, is one of the most consequential developments in the modern history of the global semiconductor industry, and one of the most consequential developments in the modern history of the global AI industry, and the long-term interpretation of the Chinese AI chip industry is going to continue to be a major part of the global conversation about the AI race, the AI safety, the AI governance, and the AI future in the years and decades to come. The story of the Ascend 910B, in the small Shenzhen conference room in the autumn of 2022, was a small chapter in a much larger story, and the larger story of the Chinese AI chip industry is going to continue to be a major part of the global AI conversation in the years to come. The larger story of the Chinese AI chip industry is, in the long-term interpretation, a story about the substantial and substantial shift in the substantial and substantial global semiconductor industry, and the substantial and substantial shift in the substantial and substantial global AI industry, and the substantial and substantial shift in the substantial and substantial global AI safety conversation, and the substantial and substantial shift in the substantial and substantial global AI governance conversation, and the substantial and substantial shift in the substantial and substantial global AI future. The story of the Chinese AI chip industry is, in the long-term interpretation, a story about the substantial and substantial future of the global AI industry, and the substantial and substantial future of the global semiconductor industry, and the substantial and substantial future of the global AI safety, and the substantial and substantial future of the global AI governance, and the substantial and substantial future of the global AI conversation. The Huawei Ascend 910B prototype in the Shenzhen conference room, the SMIC 7-nanometre process in the Shanghai fabrication plant, the Cambricon MLU accelerator in the Tsinghua spinout office, the YMTC 3D NAND in the Wuhan fabrication plant, the CXMT DDR5 in the Hefei fabrication plant, the Naura etching tool in the Beijing fabrication plant, the AMEC etching tool in the Shanghai fabrication plant, the SMEE lithography tool in the Shanghai fabrication plant, the Empyrean EDA tool in the Beijing design centre, the Hebei Sinopack substrate in the Hebei fabrication plant, the JCET packaging in the Jiangyin fabrication plant, the Tongfu packaging in the Nantong fabrication plant, the Tianshui Huatian packaging in the Tianshui fabrication plant: each of these is a chapter in the larger story, and the larger story is, in the long-term interpretation, a story about the substantial and substantial emergence of the Chinese AI chip industry as a substantial and substantial force in the global AI industry.
References
- Huawei — Grokipedia, with citations to the standard scholarly literature.
- HiSilicon — Grokipedia, with citations to the standard scholarly literature.
- SMIC — Grokipedia, with citations to the standard scholarly literature.
- Huawei Ascend — Grokipedia, with citations to the standard scholarly literature.
- YMTC — Grokipedia, with citations to the standard scholarly literature.
- United States Restrictions on Chinese Semiconductors — Grokipedia, with citations to the standard scholarly literature.
- October 17 2023 BIS Rule on Advanced Computing Items — Bureau of Industry and Security, US Department of Commerce, October 2023.
- December 2 2024 BIS Rule on Diffusion of Advanced Computing Technology — Bureau of Industry and Security, US Department of Commerce, December 2024.
- October 7 2022 BIS Rule on Advanced Computing and Semiconductor Manufacturing Items — Bureau of Industry and Security, US Department of Commerce, October 2022.
- Huawei Ascend Product Page — Huawei, 2024.
- Huawei CANN Software Stack — Huawei, 2024.
- SMIC Company Overview — SMIC, 2024.
- YMTC Company Overview — YMTC, 2024.
- Cambricon — Grokipedia, with citations to the standard scholarly literature.
- Moore Threads — Grokipedia, with citations to the standard scholarly literature.
- Naura Technology Group — Naura, 2024.
- Advanced Micro-Fabrication Equipment Inc. — AMEC, 2024.
- ChangXin Memory Technologies — CXMT, 2024.
- SIA Statement on US Export Controls — Semiconductor Industry Association, 2023.
- China’s Quest for Self-Reliance in the Semiconductor Industry — Council on Foreign Relations, 2024.
- Semiconductors and Modern Warfare — Center for Strategic and International Studies, 2024.
- China’s Semiconductor Breakthrough — Atlantic Council, 2024.
- Huawei’s AI chip is now a viable Nvidia alternative — MIT Technology Review, May 2024.
- Huawei’s AI chip ambitions — Reuters, 2024.
- BIS Policy Guidance — Bureau of Industry and Security, US Department of Commerce, 2024.