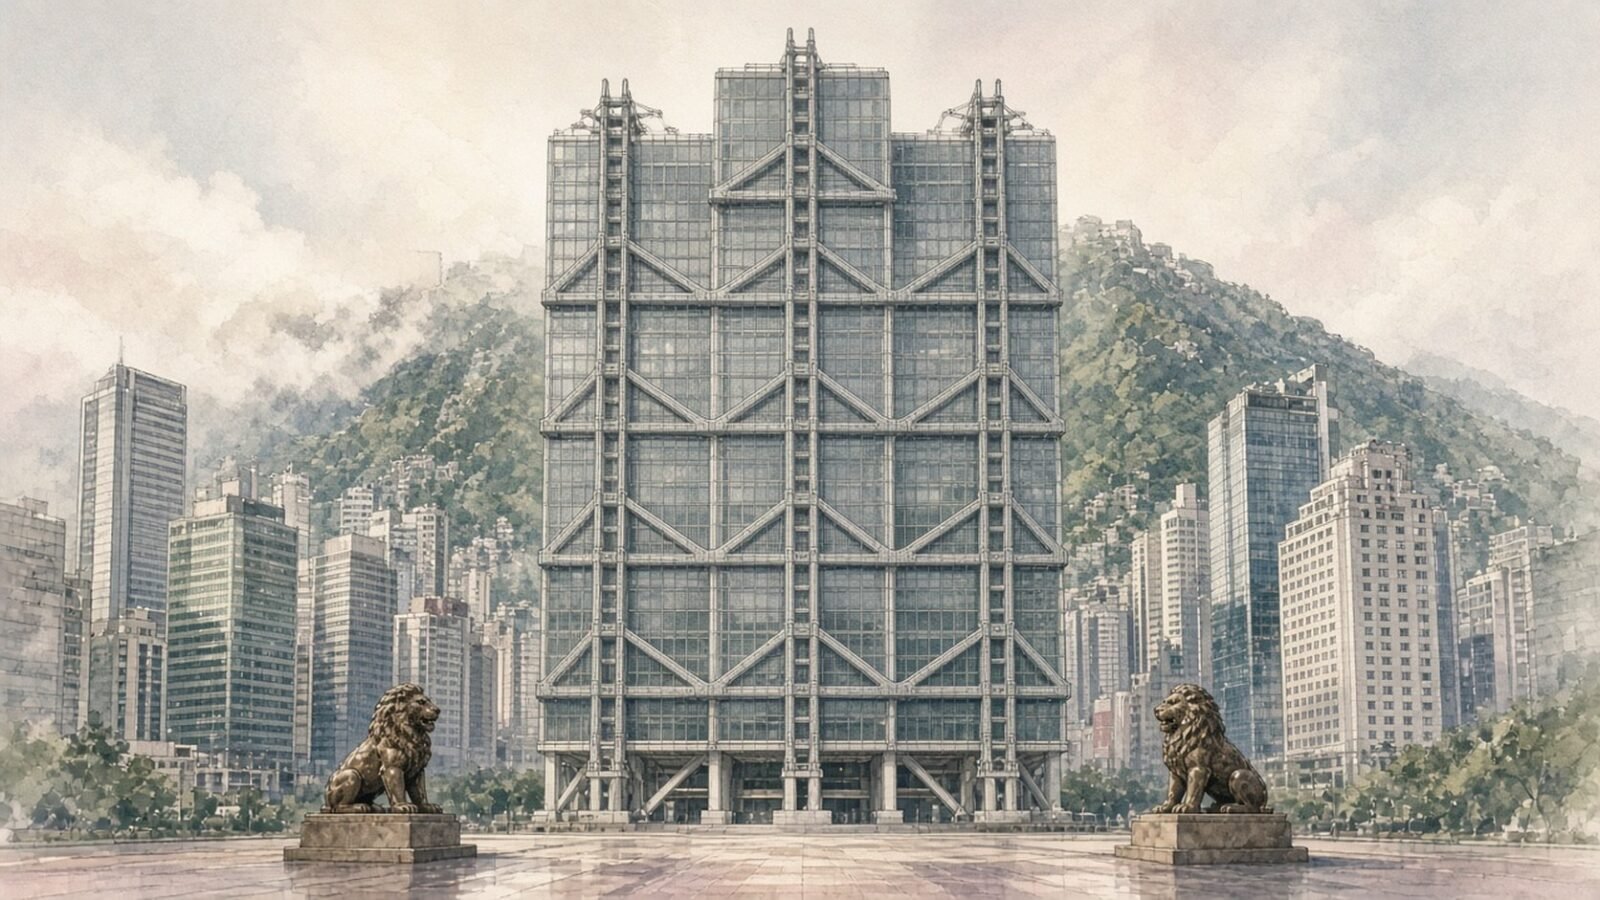
HSBC began not as an abstract financial empire but as a practical response to the extraordinary commercial growth of nineteenth century Asia. In the 1860s Hong Kong was becoming an increasingly important centre of trade between China, Britain, India, and the wider world, yet many merchants believed that the region lacked a bank designed specifically for their needs. Thomas Sutherland, a young Scottish businessman working for the Peninsular and Oriental Steam Navigation Company, saw the opportunity. He proposed the creation of a locally managed institution that could finance trade, exchange currencies, provide credit, and move money across the expanding network of Asian ports. His idea attracted support from leading merchants in Hong Kong, and the necessary capital was quickly subscribed. The Hongkong and Shanghai Banking Corporation opened for business in Hong Kong on 3 March 1865, followed by an office in Shanghai in April and a London office in July. From its earliest days the bank was therefore international in character. It was rooted in Hong Kong, deeply involved in the commercial life of China, and connected to the financial markets of Europe. That combination would become one of the defining features of its identity. Unlike many older European banks that later expanded abroad, HSBC was born at the meeting point of different regions and economies. Its earliest business consisted largely of financing trade in tea, silk, cotton, jute, sugar, and other commodities that moved through the ports of Asia. The bank also issued notes, handled foreign exchange, and developed relationships with governments and trading houses, establishing a reputation for speed, reliability, and knowledge of local markets.
During the decades after its founding, HSBC expanded with the growth of international commerce. New branches appeared in Yokohama, Calcutta, Saigon, Manila, San Francisco, New York, Lyon, Hamburg, and other commercial centres. The bank followed shipping routes, commodity markets, and migrant communities, building a network that connected Asia with Europe and North America. By the end of the nineteenth century it had become a major financial institution in the region, and its role extended beyond ordinary merchant banking. HSBC participated in government finance, handled public accounts, and helped arrange loans for infrastructure projects such as railways, ports, and public works. Its ability to move capital across borders made it useful to governments and companies operating in rapidly changing economies. One of the most influential figures in this period was Thomas Jackson, who served several terms as chief manager between 1876 and 1902. Under his leadership the bank strengthened its reserves, expanded cautiously, and developed a culture that placed great importance on liquidity and financial resilience. That caution proved valuable during periods of financial panic. The late nineteenth century was marked by repeated banking crises, currency instability, political upheaval, and sudden changes in commodity prices. HSBC survived these shocks partly because it tried to maintain strong capital and partly because its business was spread across several markets. Its early history therefore established a pattern that would recur many times: rapid international growth followed by a renewed emphasis on discipline, reserves, and the ability to withstand unexpected crises.
The opening decades of the twentieth century brought both opportunity and danger. HSBC continued to expand its influence in China and elsewhere in Asia, but the political environment became increasingly unstable. The fall of the Qing dynasty, the emergence of the Republic of China, regional conflicts, the First World War, global economic disruption, and later the Great Depression all affected the bank and its customers. HSBC nevertheless remained closely associated with the financing of Asian trade. In Shanghai it became one of the most prominent foreign banks, and its grand building on the Bund, opened in 1923, symbolised the institution’s confidence and status. The building was designed to project permanence at a time when the city was one of the great commercial centres of the world. Yet the apparent solidity of the bank’s architecture contrasted sharply with the uncertainty surrounding it. Currency systems shifted, governments changed, and economic nationalism challenged foreign institutions. HSBC had to operate across jurisdictions with different legal systems and political priorities. This experience strengthened its habit of relying on local knowledge while maintaining an international network. The bank’s senior managers were expected to understand not only finance but also shipping, trade patterns, political risk, and the customs of the communities in which they worked. By the 1930s the institution had become far more complex than the merchant bank founded in 1865, but it still depended heavily on the movement of goods and money across borders. Its fortunes were inseparable from the economic life of Asia, and that connection would soon expose it to the most severe crisis in its history.
The Second World War transformed HSBC’s world. The Japanese occupation of Hong Kong in December 1941 forced the bank’s headquarters to cease normal operations, and many members of its staff were interned. Sir Vandeleur Grayburn, the bank’s chief manager, and other employees endured imprisonment under extremely harsh conditions. Some died during the occupation. Operations that could continue were directed from London, while branches in different parts of the world faced their own wartime restrictions and dangers. The experience became one of the defining episodes in HSBC’s institutional memory because it tested both the loyalty of its employees and the practical value of its international structure. When the war ended in 1945, the bank returned to Hong Kong and helped finance the territory’s reconstruction. The economic environment, however, was changing rapidly. The Communist victory in China in 1949 sharply reduced the bank’s mainland business, and many of the old trading relationships that had supported HSBC before the war disappeared. Hong Kong itself began to evolve from a trading port into a manufacturing centre, driven in part by capital, skills, and entrepreneurs arriving from mainland China. HSBC adapted by financing factories, exporters, property development, and new forms of local enterprise. Rather than simply returning to the model that had existed before the war, the bank became more deeply involved in the domestic economy of Hong Kong. This ability to alter its business while preserving its identity as an international institution was crucial to its survival.
The postwar decades changed banking technology and consumer expectations, and HSBC increasingly became a modern retail as well as commercial bank. In Hong Kong the growth of manufacturing, real estate, and personal incomes created demand for mortgages, savings accounts, consumer credit, and a broader range of financial services. The bank also adopted new technology. In 1967 an IBM computer was installed at the Hong Kong head office, allowing customer accounts to be processed electronically and helping create a system in which customers could use different branches more easily. This shift may appear ordinary today, but it represented a major change in how a large bank operated. HSBC also expanded through investment in other institutions. In 1965 it acquired a majority stake in Hang Seng Bank after a crisis in Hong Kong’s banking sector. Hang Seng remained a distinct brand and became an important part of the wider group. At the same time, HSBC faced a strategic question. Its historic strength was in Hong Kong and Asia, but the global financial system was becoming more integrated, and large banks were increasingly competing across continents. If HSBC wanted to remain influential, it needed a broader base. The answer would come through acquisitions, especially in North America and Europe, that transformed the scale and character of the organisation.
The first major step toward becoming a truly global banking group came in the United States. HSBC acquired a controlling interest in Marine Midland Bank in 1980 and completed full ownership in 1987. Marine Midland gave the group a substantial American presence and reduced its dependence on Hong Kong. The acquisition was part of a broader strategy to build a network capable of serving multinational companies and increasingly international customers. The most dramatic transformation, however, occurred in Britain. In 1991 HSBC created HSBC Holdings plc as a new parent company for the group. The restructuring was designed in part to prepare for a possible acquisition of Midland Bank, one of Britain’s largest banks. In 1992 HSBC completed the purchase of Midland in a deal worth about £3.9 billion, one of the largest banking acquisitions of its time. HSBC Holdings became headquartered in London, while The Hongkong and Shanghai Banking Corporation remained a central operating bank within the group. The Midland acquisition also gave HSBC an extensive British branch network and millions of new customers. During the following years the group increasingly adopted the HSBC name across its businesses. Midland was renamed HSBC Bank in 1999, and the red and white hexagon became the unifying symbol of a global brand. By the end of the twentieth century, the bank founded to finance Asian trade had become one of the largest financial groups in the world.
The global expansion accelerated in the late 1990s and early 2000s. HSBC acquired Republic New York Corporation, expanded in France through the purchase of Crédit Commercial de France, strengthened its presence in Mexico, and bought businesses in several other markets. The logic behind these acquisitions was clear: HSBC wanted a balanced global network with strong positions in Asia, Europe, North America, Latin America, and the Middle East. Yet one acquisition would later become a major source of difficulty. In 2003 HSBC acquired Household International, a large United States consumer finance company. Household specialised in lending to consumers, including many borrowers who were considered higher risk. At first the deal seemed to give HSBC rapid access to the vast American consumer credit market. As the United States housing market weakened, however, losses mounted. The problems at Household, later known as HSBC Finance, became especially severe during the global financial crisis that began in 2007. HSBC eventually wound down much of the business. The episode demonstrated the danger of expanding into markets where the group’s traditional strengths in trade finance and international banking offered less protection. It also became a powerful example of how an acquisition that looked strategically attractive during a period of economic confidence could create enormous costs when conditions changed.
The global financial crisis of 2007 and 2008 was one of the greatest tests in HSBC’s modern history. The bank suffered heavy losses in its American consumer finance operations, particularly as mortgage defaults increased and credit markets froze. Yet the group entered the crisis with significant earnings from Asia and other parts of its network, and it did not require a direct British government bailout. Even so, the scale of the crisis forced HSBC to strengthen its capital. In 2009 it raised roughly 17.8 billion United States dollars through a major rights issue, one of the largest such capital raisings in British corporate history. Management closed or sold businesses, reduced exposure to weaker markets, and placed greater emphasis on regions connected to international trade and faster economic growth. The crisis changed the bank’s strategic thinking. For years HSBC had sought geographic breadth almost as an end in itself. After the crisis it became more selective, asking whether each market truly contributed to the network. This led to years of restructuring, disposals, and cost reduction. The bank’s leaders increasingly argued that HSBC’s real advantage was not simply being present in many countries, but connecting customers across them. That distinction became central to the group’s strategy. It also encouraged renewed emphasis on Asia, where HSBC retained deep historical roots and where economic growth and wealth creation were reshaping global finance.
Another major challenge emerged from regulatory and compliance failures. In December 2012 HSBC Holdings and HSBC Bank USA entered into a deferred prosecution agreement with the United States Department of Justice after admitting serious failures in anti money laundering controls and violations related to sanctions. The bank agreed to forfeit 1.256 billion United States dollars and accepted additional penalties imposed by other authorities, bringing the wider financial cost to almost 2 billion dollars. The case described weaknesses in the monitoring of transactions and correspondent banking relationships and became one of the most damaging episodes in HSBC’s modern reputation. HSBC invested heavily in compliance systems, financial crime controls, staff, monitoring, and central oversight. A corporate monitor was appointed, and the group spent years reshaping its internal processes. The scandal also exposed a tension that had existed within HSBC for much of its history. The bank had traditionally given considerable autonomy to local operations because local knowledge was one of its strengths. Yet a global institution also needed common standards capable of controlling risk across many jurisdictions. In the years after 2012 HSBC became more centralised in several areas, especially compliance and risk management. The episode showed that international reach could be both an advantage and a vulnerability. A network that connected many markets also created more points at which failures of supervision could become global problems.
During the 2010s HSBC continued to simplify its operations. It sold businesses, reduced its presence in some countries, and concentrated resources on activities where its international network offered a clear advantage. The group also had to adapt to a banking environment transformed by smartphones, digital payments, online investment platforms, financial technology companies, and changing customer expectations. Traditional branches became less central as more services moved online. HSBC invested in mobile banking, data systems, cyber security, and digital tools for corporate customers. At the same time, the bank faced prolonged low interest rates in many developed economies, tighter capital requirements, and pressure from investors to improve profitability. Its global structure remained valuable but expensive. Each country involved regulators, technology systems, legal entities, compliance obligations, and management costs. These pressures pushed HSBC toward a more focused definition of what it meant to be a global bank. Rather than trying to offer every service in every market, it increasingly concentrated on wealth management, commercial banking, transaction banking, trade finance, and services for internationally active companies and affluent customers. Asia, especially Hong Kong and mainland China, remained central to this strategy, while the United Kingdom continued to serve as the group’s second home market and the location of its corporate headquarters.
The relationship between HSBC’s Asian heritage and its British corporate base became one of the most closely watched aspects of the bank in the twenty first century. HSBC was founded in Hong Kong, earns a substantial share of its profits in Asia, and has long been one of the most important financial institutions in Hong Kong. Yet HSBC Holdings is headquartered in London and is regulated within a British and international framework. This dual identity has often required careful navigation of different political, regulatory, and economic environments. The bank has had to manage expectations from shareholders, governments, customers, and employees across regions that do not always share the same priorities. At various moments investors have debated whether the group should be reorganised or divided, while management has generally defended the value of the international network. The strategic answer has been to simplify without abandoning the connections that make HSBC distinctive. In 2024 the group announced another major reorganisation, and from 1 January 2025 it began operating through four main businesses: Hong Kong, United Kingdom, Corporate and Institutional Banking, and International Wealth and Premier Banking. The new structure was intended to reduce duplicated management and make decision making faster. It also made the group’s priorities unusually clear. Two businesses were built around its historic home markets, while the other two were designed around the international movement of capital, companies, and wealthy customers.
By 2026 HSBC remained one of the world’s largest banking and financial services organisations. It served roughly 41 million personal, wealth, and corporate customers across 56 countries and territories and employed about 211,000 people. Its modern activities ranged from current accounts and mortgages to corporate lending, payments, trade finance, investment banking, asset management, private banking, and insurance. In many respects the institution had travelled an extraordinary distance from the small group of merchants who subscribed capital in Hong Kong in 1865. Yet there was also a remarkable continuity in the underlying idea. HSBC still presented its greatest strength as the ability to connect customers across borders, currencies, and markets. A company exporting goods, an entrepreneur investing abroad, a family managing wealth across countries, or a multinational corporation moving cash between subsidiaries all represented modern versions of the cross border needs that inspired the bank’s creation. Technology had changed the speed of finance beyond anything Thomas Sutherland could have imagined, but the basic commercial problem remained familiar: people and businesses needed a trusted institution capable of moving money safely through a complicated international system.
HSBC’s biography is therefore a story of both continuity and reinvention. It began as a Hong Kong bank created to serve the trade of Asia, grew into a regional institution, survived war and political upheaval, expanded into consumer and corporate banking, and eventually became a global financial group headquartered in London. Its history includes periods of impressive growth, architectural ambition, technological change, and successful international expansion. It also includes costly mistakes, regulatory failures, and strategic retreats. The acquisition of Household International revealed the risks of moving too far from areas of established expertise. The 2012 compliance settlement showed how weak controls in one part of a global network could damage the reputation of the whole institution. The years of restructuring that followed demonstrated how difficult it is to manage a bank whose size is itself both an asset and a burden. Through all these changes, HSBC has repeatedly returned to the same central question: what is the value of being international? Its answer has evolved from a network of physical branches serving ships and merchants to a digitally connected system serving corporations, investors, and individuals. More than a century and a half after its founding, HSBC remains shaped by the geography of its birth. Hong Kong, Shanghai, London, and the trade routes between East and West are not merely chapters in its past. They explain the logic of the institution itself, a bank built around movement, connection, and the belief that finance can bridge distant markets.