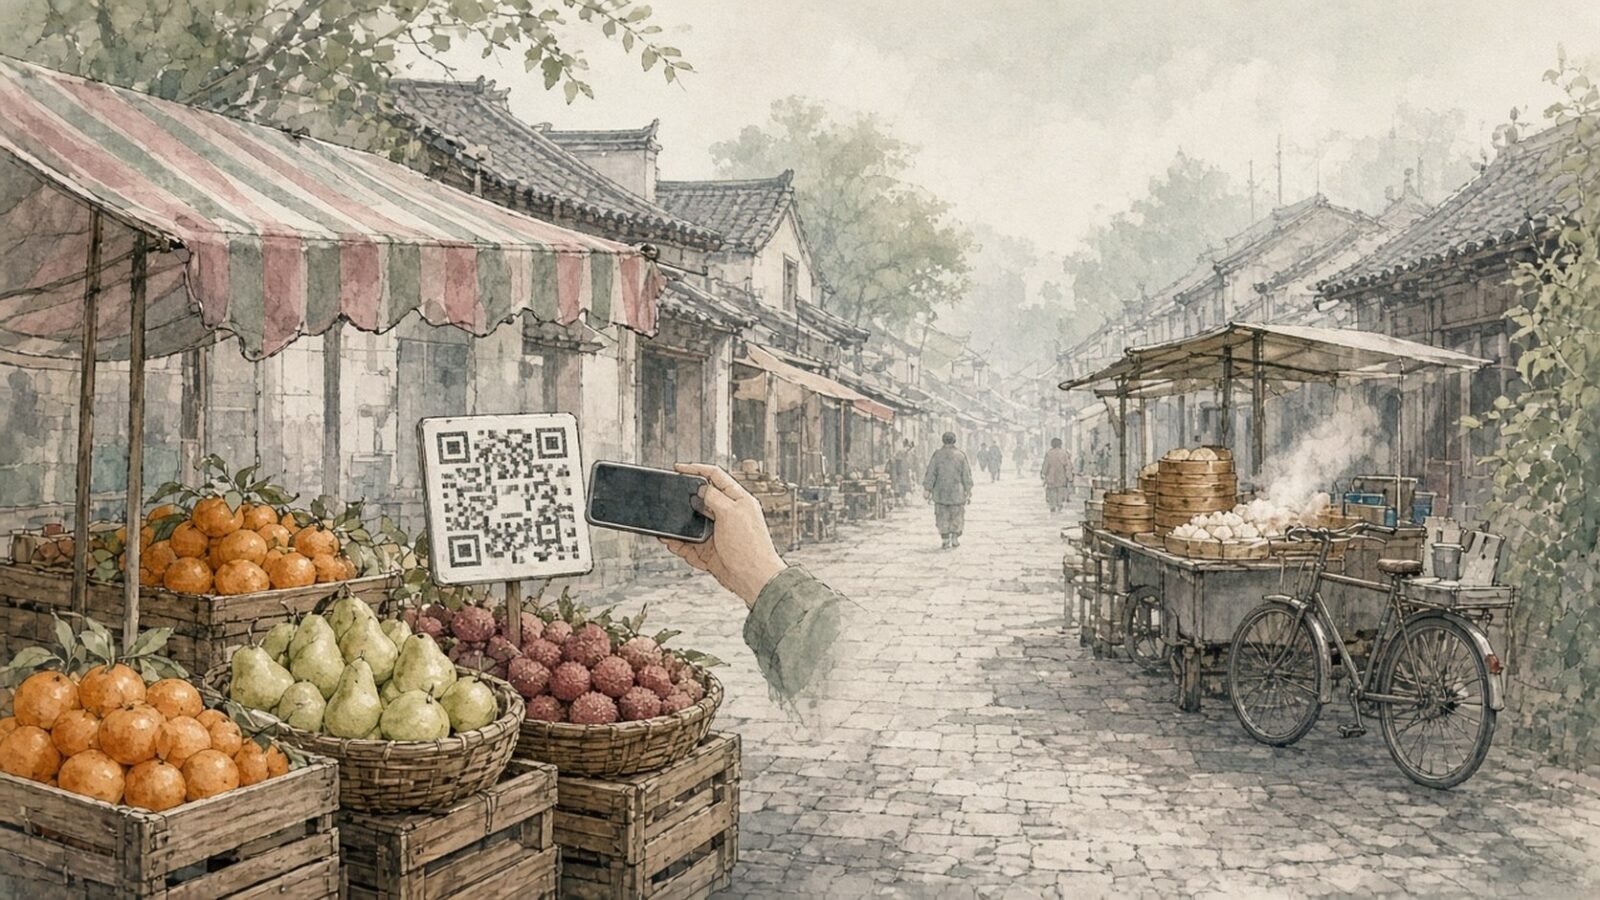
Walk down a market street in any Chinese city today and you will see something that still startles visitors. The fruit vendor, the dumpling stall, the man sharpening knives on a bicycle, even the beggar sitting at the temple gate: each has a printed square of paper pinned within reach, patterned with black and white modules. The customer points a phone at the square, hears a synthetic voice announce the amount aloud, and walks away with the goods. No card changes hands. No signature is scrawled. Increasingly, no banknote moves either. In the space of a decade and a half, the world’s oldest cash civilisation, the one that invented paper money under the Song dynasty, became the first large economy in which paper money is close to optional.
The statistics are by now familiar but remain extraordinary. In 2016, Chinese consumers spent about 5.5 trillion US dollars through mobile payment platforms, roughly fifty times the 112 billion that passed through equivalent systems in the United States. By 2017 the total value of mobile payments inside China had reached 120 trillion yuan, some 17.5 trillion dollars, according to industry tallies cited in the international press. QR codes appeared on donation boxes in Buddhist temples, on the bowls of street beggars, and in the windows of wedding cars collecting digital gift money. Pony Ma, the founder of Tencent, boasted in 2015 that even beggars used his company’s QR codes, and reporters who went looking found he was not exaggerating.
How did a country that barely had credit cards come to lead the world in paying by phone? The answer is not a single invention. It runs through escrow, printed squares, a red envelope ambush and a very old reflex, and it ends with China skipping the credit card entirely. It is a layered story about trust, infrastructure, timing, and a distinctly Chinese tolerance for letting private companies build systems the state only later decides to govern. It is also, as this series has argued again and again, a story about standardisation. China has been here before.
The card that never arrived
To understand the leap, first notice what China skipped. In America and Western Europe, the credit card arrived in the 1950s and 1960s and spent half a century digging itself into the economy. By the time the smartphone appeared, the West had built an immense physical estate: card readers in every shop, networks connecting them, banks issuing plastic to nearly every adult, and consumers so habituated to swiping that the card felt like the natural end point of money itself. That estate was an asset and an anchor. It worked well enough that replacing it was hard to justify, and it was expensive enough that the companies who owned it had every reason to defend it.
China’s card era was thin and late. UnionPay, the national bank card network, was founded only in 2002, stitching together regional systems so that cards issued in one province could be used in another. Card ownership grew quickly after that, but the surrounding estate never reached Western depth. Small merchants often refused cards because the point of sale terminal cost money and the processing fees bit into thin margins. Consumers, for their part, had little of the attachment to plastic that Americans carried. In 2010 the overwhelming majority of Chinese retail still ran on cash, withdrawn from a bank branch and counted out by hand.
This thinness looked like backwardness. It turned out to be freedom. When the smartphone arrived in force after 2010, China had no entrenched card estate to protect and no habit of swiping to overcome. The phone did not have to defeat the credit card. It only had to defeat cash, and cash, as every shopkeeper knows, is slow, dirty, easy to steal, and impossible to spend online.
There is a name for this pattern. Economists call it leapfrogging: a country that never built the old infrastructure adopts the new one faster than countries that did, precisely because there is nothing to tear up. Africa skipped the landline and went straight to the mobile phone. China skipped the personal cheque, largely skipped the credit card, and went straight from banknotes to the phone. The lesson repeats throughout modern economic history, but nowhere on this scale.
Strangers, sewing machines, and the escrow account
The deeper problem that mobile payments solved in China was not convenience. It was trust.
When Taobao, the consumer marketplace run by a young company called Alibaba, began to grow in 2003 and 2004, it faced a difficulty that eBay in America had largely inherited rather than solved. Chinese shoppers did not know the strangers selling to them, and they had no reason to trust them. There was no mature credit bureau, little experience of consumer credit, and a widespread and not irrational assumption that an unseen seller would take the money and send nothing, or send bricks in a box. Sellers, equally, feared buyers who would receive goods and claim they never arrived.
Alipay, launched in 2004, was the answer, and its answer was escrow. The buyer’s money did not go to the seller at all. It went to Alipay, which held it and told the seller to ship. Only when the buyer confirmed that the goods had arrived as described did Alipay release the funds. The platform became, in effect, a trusted third party standing between every pair of strangers, guaranteeing both sides. This single design decision mattered more than any technology that followed. It taught hundreds of millions of Chinese consumers that an app run by a private company could be trusted with their money, more trusted, in daily practice, than the stranger across the counter.
The comparison with the West is instructive. PayPal solved a version of the same problem for eBay, but American buyers already had credit cards with chargeback rights, so escrow was a convenience rather than a revelation. In China it was the foundation of an entire commercial culture. Once that culture existed, everything else followed. By 2013 Alipay’s companion money fund, Yu’ebao, which let users park their wallet balances at money market rates with instant access, had become the largest money market fund in the world by assets, drawing savings from ordinary people who had never been offered an attractive place to put them.
A system built to make strangers trade sewing machines safely had become a bank in all but name.
The printed square that ate the terminal
If escrow solved trust online, the QR code solved cost in the street.
The West’s answer to paying by phone was NFC, near field communication, the tap of a phone against a specialised reader. It is elegant technology and it failed to conquer China, for a simple reason: both sides need the hardware. The merchant must buy or rent a terminal that can read the tap, which put NFC in the same cost trap as the card machine before it. China went the other way. The QR code requires nothing on the merchant’s side except a printout. A street vendor can register with Alipay or WeChat Pay on a borrowed phone, print the code at a copy shop for a few fen, laminate it, and be accepting digital payment within the hour. The customer bears the hardware cost, in the form of the smartphone she already owns.
This asymmetry is the whole secret of the street scene described at the start of this essay. The QR code moved the cost of the payment network from the merchant to the customer, and since the customers were already carrying smartphones, the network’s marginal cost of adding a new merchant fell to nearly zero. No sales team had to visit the dumpling stall. No terminal had to be installed, serviced, or connected. Payment acceptance became a cottage industry of printed paper.
Western analysts who visited Chinese malls in the mid 2010s noticed the gap at once. American mobile payment adoption among smartphone users hovered around twenty percent, and the stores they visited were a patchwork of terminals old and new. In Hangzhou, Alibaba’s home city, the same analysts found QR codes on everything from taxi dashboards to street snacks. The future of retail, one industry report concluded, was not being prototyped in California. It was already running, at full scale, in Zhejiang.
There is an irony here that the series regular will savour. The QR code was invented in Japan in 1994 by Denso Wave, a Toyota affiliate, to track car parts through factories. Like the compass, the stirrup, and printing itself, a technology drifted to China and found its world changing application there. China did not invent the printed square. China did what it has always done with useful tools: standardised it, scaled it, and put it in every hand.
The red envelope blitz
By 2013 Alipay dominated online payment, and its position looked unassailable. Then came one of the most celebrated ambushes in business history.
WeChat, Tencent’s messaging app, was where China talked. It was not where China paid. In the weeks before the Spring Festival of 2014, Tencent quietly added a feature that digitised the hongbao, the red envelope of cash that Chinese families exchange at New Year. The digital version kept the ritual and added a game: a sender could drop a sum into a group chat and let the app split it randomly among whoever grabbed fastest. It was delightful, it was social, and it required every player to link a bank card to WeChat Pay.
Over that single holiday, millions did. Jack Ma, Alibaba’s founder, called the campaign a Pearl Harbor attack on his company, and the metaphor was apt in both its surprise and its consequences. Tencent had used a festival ritual older than the dynasty system to smuggle a payment network into the pockets of half the country. Within two years the two companies stood locked in a duopoly that persists today: Alipay strong in commerce and finance, WeChat Pay strong in social transfers and daily small payments, together handling well over ninety percent of Chinese mobile payment volume.
The hongbao episode deserves a moment’s reflection, because it illustrates something this series keeps encountering. In China, new systems do not arrive as abstractions. They arrive wearing the clothes of old customs. The digital red envelope worked because the paper red envelope had worked for centuries. The QR code on the temple donation box works because the donation box was always there. Technology in China succeeds by finding the ritual groove already worn into the culture and running along it.
Peak cashless and its discontents
By 2018 or so, the transformation was complete enough to generate its own problems, and the problems are as revealing as the success.
The first was exclusion. Elderly people, the rural poor, and the millions of migrant workers whose lives ran on cash found shops that would no longer take it. Foreign visitors, arriving with foreign cards and foreign phones, discovered that they could barely buy a bottle of water in Shanghai, since both dominant apps expected a Chinese bank account. The People’s Bank of China was eventually forced to remind the market that refusing cash is illegal, and from 2018 it ran enforcement campaigns against merchants who declined banknotes. A payment system that forgets the poor is not progress, whatever its elegance.
The second problem was concentration. Two private companies now sat astride the daily commerce of 1.4 billion people. They knew what everyone bought, when, and from whom. They had become banks, insurers, lenders, and investment platforms while being regulated, for much of the run, as technology companies. The state’s patience with this arrangement, never unlimited, visibly expired at the end of 2020. Days after Jack Ma gave a speech in Shanghai comparing Chinese banks to pawnshops, regulators suspended the 37 billion dollar stock market listing of Ant Group, Alipay’s parent, which had been set to be the largest public offering in history. Ma largely vanished from public view for months. The message was not subtle, and it was not lost on anyone: in China, the rails of money belong, ultimately, to the state.
The third problem was structural. Money held in payment apps had, in the early years, sat in pooled accounts that the platforms could invest and from which they quietly profited. Regulators ended this in stages, culminating in a requirement, fully in force by 2019, that customer balances be backed one hundred percent by reserves at the central bank. In 2018 the platforms were also required to route their clearing through NetsUnion, a centralised clearing house under central bank oversight, ending the era in which transactions settled opaquely inside private ledgers.
The pattern is worth naming, because it recurs through this entire series. China lets a new system grow wild until its shape is clear, then builds the dykes. The Warring States let iron tools spread before the First Emperor standardised the axle gauge and the script. The republic of apps was allowed to flourish until the state understood it, at which point the state took back the rails.
The sovereign strike back: the digital yuan
The final act of this story, still being written, is the state’s own entry into the field.
The digital renminbi, known as e-CNY, is a central bank digital currency: legal tender issued directly by the People’s Bank of China, held in wallets on the phone, spendable in principle without any commercial platform at all. Pilots began in Shenzhen and a handful of other cities in 2020, distributing money by lottery in digital red envelopes, an irony that needs no emphasis by now. By the end of 2022, about 13.6 billion e-CNY were in circulation across an expanding set of pilot zones, small against the trillions flowing through Alipay and WeChat Pay, but growing with deliberate intent.
The strategic logic is plain. If money lives inside private apps, the state sees transactions only through those companies’ cooperation. If money lives in a central bank wallet, the state sees directly, controls directly, and can programme features, expiry dates on stimulus payments, targeted transfers, that no private network would permit itself. The e-CNY is also a hedge for the international system: a renminbi that moves digitally could someday settle trade without touching the American dominated banking pipes, a prospect Beijing studies closely.
Whether ordinary Chinese will voluntarily adopt the state wallet, when the two private ones work so smoothly, is an open question. History suggests a cautious answer. China is very good at building systems and fairly patient about making them habitual. The examination system took centuries to become the spine of the state. The digital yuan has time.
Why the West watched instead
The obvious question is why the United States and Europe, with all their technological prowess, did not do this first. The answer is the mirror image of China’s story.
The West had the card estate, and the card estate fought back. Every party in the Western payment chain, the issuing banks, the card networks, the terminal makers, the merchants, had revenue depending on the swipe, and no party could move without the others. Apple Pay and its rivals layered the phone on top of the card rather than replacing it, which is why paying by phone in the West feels like a slightly faster way to do the same old thing. American consumers, meanwhile, trusted their cards and their chargeback rights; the escrow revelation was unnecessary because the trust problem had already been solved by other means. And the social vehicle was missing: no Western app combined messaging, identity, and commerce the way WeChat did, so there was no red envelope moment, no ritual to ride.
China had none of these brakes. It had an unsolved trust problem, no card habit to defend, merchants priced out of terminals, a messaging super app, a festival custom ready to digitise, and a government that, for a crucial decade, watched with interest rather than intervening. The leapfrog happened because the conditions for it were complete, and they were complete in exactly one place.
The axle gauge of money
This series began with the Yellow Emperor and a family tree half myth, half memory. It passed through the examination halls that sorted a billion ambitions, the First Emperor’s standardised axles and scripts, and the treasure fleets that ruled the ocean and then burned. It ends, for now, with a printed square of paper taped to a fruit cart.
The thread is the same one it has always been. China’s recurring genius is not invention but consolidation: the taking of a scattered practice and the making of it uniform, universal, and unavoidable. The First Emperor standardised the gauge of cart axles so that goods could move across the empire without breaking the roads. The QR code standardised the interface of payment so that money could move across the economy without friction. One was imposed by decree and enforced by law. The other spread vendor by vendor because it was cheap and it worked. Both did the same thing. They made the empire interoperable.
The beggar’s QR code and the emperor’s axle gauge are the same object, two thousand years apart: a standard so convenient that resisting it costs more than accepting it. The tools change. The reflex does not. Whatever China does next with money, with artificial intelligence, with power itself, expect the pattern to hold. Let a thousand experiments bloom, watch which one takes, then make it the gauge of the realm.
References
- Mobile payments in China, Grokipedia
- Alipay, Grokipedia
- WeChat, Grokipedia
- Ant Group, Grokipedia
- Digital renminbi, Grokipedia
- UnionPay, Grokipedia
- Red envelope, Grokipedia
- Beggars with QR codes: China’s poor ditch tin bowls for mobile wallets, Financial Express
- China is showing the rest of the world how to build a cashless society, New Scientist
- Looking for the future of retail in Chinese malls, IPG Media Lab